
The Thai Life Insurance Association advises flood victims to check their policy loan eligibility before surrendering their insurance policy.

The Thai Life Insurance Association advises policyholders experiencing financial difficulties due to the floods that they may consider taking out a loan against their life insurance policy, provided the policy has a cash value and the terms and conditions allow for a loan without requiring a guarantor or other assets. However, they should check the interest rates and plan their repayment carefully, as this will affect the benefits and coverage under the policy.
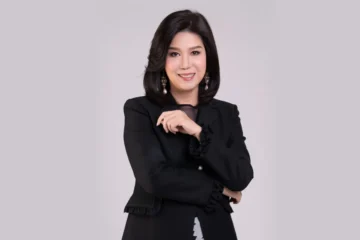
October 5, 2569 – Ms. Nusra (Assakul) Banyatpiyapoj, President of the Thai Life Insurance Association, revealed that policyholders affected by the floods, especially families whose income has been disrupted and who face expenses for restoring their livelihoods, should check their eligibility for life insurance loan options. This can provide a liquidity boost during times of need, reduce reliance on high-interest informal loans, and preserve their family's financial security.
For policyholders with active life insurance policies that have a cash value and offer loan terms, they can contact their life insurance company to request this benefit without needing a guarantor or other assets. The cash value and loan amount depend on the type of insurance policy, the premium payment period, and the policy terms. Policyholders should therefore inquire with their insurance company, as different policy types offer different benefits.

Ms. Nusra advised that policy loans have interest rates specified in the contract and can be repaid in installments or as a lump sum according to the company's terms. The policy also maintains coverage as long as the policyholder fulfills the conditions regarding premium payments and debt management. Those needing temporary working capital should check their policy loan eligibility before deciding to surrender the policy, as surrendering terminates coverage and the amount received may be less than the premiums paid. Utilizing policy loans appropriately can alleviate immediate financial hardship while preserving future coverage.
However, policyholders should only borrow what is necessary and plan to repay the principal and interest when their financial situation improves. This is because outstanding debt will be deducted from the benefits that the company must pay according to the policy. If the total loan amount, including interest, reaches a certain threshold, the policy may be terminated according to the terms of the contract.
"The association advises policyholders to check their eligibility and understand the terms and conditions before making a decision. They should inquire about the coverage amount, interest rate, repayment method, and required documents directly from the life insurance company."
Read related news